
✨ Local Trust. National Reach.
A mortgage should feel stress-free
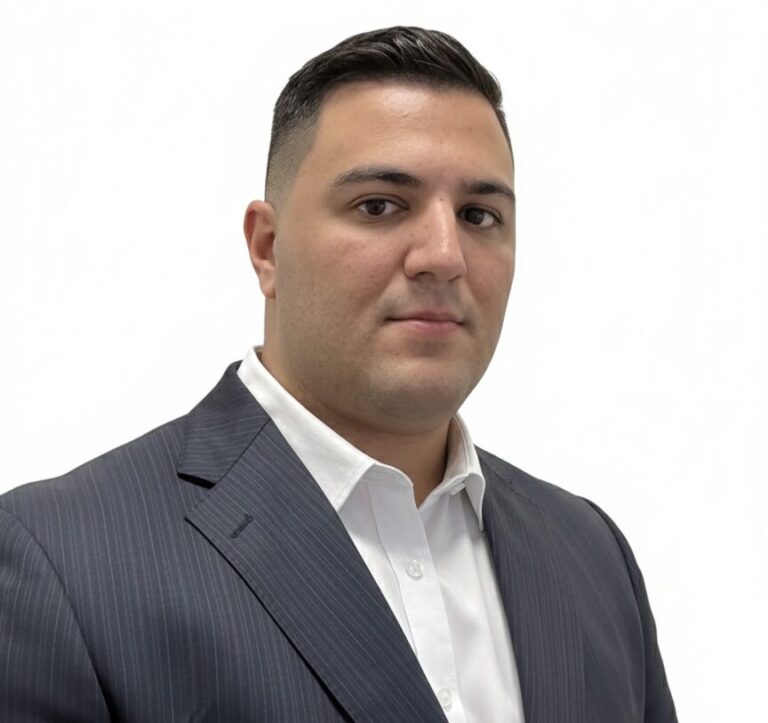
I am John Kleopoulos, a licensed mortgage loan originator. No call center, no rate games, no getting handed off. Just a real person who explains your options honestly and stays with you from the first question to the closing table.
No credit pull. No obligation. I’ll get back to you personally — same day.
⭐ Backed by Loan Factory’s 21,000+ five star reviews
Less Stress
One point of contact, application to close.
More Clarity
Plain-language comparisons, up front.
Confidence
Text or call me directly — 7 days a week.
240+ lenders.
All competing for you.
What's Actually Different Here
Why Shopping Multiple Lenders Actually Matters
Not company talking points — independent research.
50%
Never Find Out
The CFPB found that almost half of borrowers don't compare lenders at all — meaning they never learn if they got the better deal or the worse one. (CFPB, 2024)
$6,500
The Cost of Not Shopping
Federal Reserve researchers found identical borrowers, on identical loans, on the same day, can pay this much more in upfront costs — just for picking the wrong lender first. (Federal Reserve research, Bhutta, Fuster & Hizmo)
$36,000+
Over the Life of the Loan
A rate gap of just over $100 a month — which Urban Institute researchers found is common between identical borrowers — adds up to tens of thousands of dollars over a 30-year mortgage. (Urban Institute analysis of federal loan data)
87%
Overpaid Last Year
A 2026 Bankrate study found 87% of Americans who got a mortgage in 2025 paid more than necessary — including the majority of well-qualified conventional borrowers. (Bankrate, 2026)
We put our money where our mouth is.
If we can't beat another offer, you'll receive $2,000.
Terms & ConditionsMortgage Options
What You are Looking to Do
Whether you are buying your first place, lowering a payment, or growing a rental portfolio — here's where to start.
01
Buy
Find the right loan for your first home, your next home, or anything in between — VA, FHA, conventional, and more.
02
Refinance
Lower your payment, pull out cash, or tap your equity — with the real math shown before you decide anything.
03
Invest
Financing built for rental and investment properties, including loans that qualify on the property's income.
Jumbo · Investors · Business Owners
Is your bank's offer really the best one?
Every lender sets its own pricing and guidelines for jumbo, investor and self-employed loans. Your bank is quoting from its own rate sheet, not the market's, and on a $1 million loan, a quarter-point adds up to roughly $59,000 over 30 years.
Where a single lender falls short
"My bank already gave me a rate."
That's one quote from one rate sheet. Measuring it against 240+ lenders is how you find out whether it's competitive, and the Best Price Guarantee backs it.
"My tax returns understate what I earn."
Write-offs are smart for taxes and costly for conventional underwriting. Bank-statement and asset-based programs can qualify you on what you actually have.
"I'm buying in an LLC or growing past 10 properties."
DSCR loans qualify on the property's rental income, not your personal income. Many lenders allow LLC closings, and some go beyond the 10-financed-property cap conventional loans impose.
"I need to move fast."
Waterfront and high-end listings don't wait. A strong pre-approval and one direct line to the person handling your file mean you're not losing the house to a slow bank.
Our Approach
Not sure where to start? That's normal.
If you feel behind or confused, you're not. Almost everyone is. Most people I talk to think everyone else has this figured out. They don't. Nine out of ten buyers don't fully understand closing costs. Most think they need 20% down — most programs don't require anywhere near that. If your credit isn't perfect, or your income doesn't come from a simple W-2, that's not a disqualifier, it's just a starting point for the conversation. There's no dumb question here, and no judgment about where your finances stand today.
Not Enough Savings? Common.
Most buyers think they need 20% down. Most programs don't come close to requiring that — some need as little as zero.
Imperfect Credit? Also Common.
Your credit isn't a locked door. It's one factor among several, and there's usually a path even if it's not where you want it to be.
Self-Employed Income? Still Counts.
Bank-statement and asset-based programs exist for exactly this. Non-traditional income isn't a disqualifier — it just needs the right kind of loan.
Run your own numbers
Estimate a monthly payment, or get a feel for what might fit your budget. Either way — these are educational estimates, and when you want a real number, I'll base it on your actual file.
How It Works
No surprises. No judgment. Just five honest steps.
Here's exactly what happens when you reach out — nothing hidden, nothing you're not ready for.
Talk
Tell me where you're at, no matter how messy it feels. Credit questions, income questions, "I don't even know where to start" questions — all fair game, all judgment-free.
Understand
I explain your real options in plain English — including the ones you didn't know existed. No jargon, no lecture about what you "should" have done differently.
Decide, on your timeline
Ready now or ready in six months — I'm not going anywhere either way. There's no pressure to move faster than you're comfortable with.
Get pre-approved
Once you're ready, I get you a real pre-approval letter — one agents actually take seriously.
Close, without the runaround
I coordinate with your agent, title, and underwriting, so closing day is the easy part, not the scary part.
Even If You Are Months Away
Talk to me early. Even if you're not ready yet.
The best time to talk to me isn't when you're ready to apply. It's before you start looking. If you're still a few months out, still saving, still deciding whether now is the right time — that's exactly when a conversation helps most. No pressure to move faster than you want to.
A company you can trust.
You work with me directly. Behind me is Loan Factory, one of the largest mortgage brokers in the country.
Company figures for Loan Factory, Inc. (NMLS #320841), per loanfactory.com. Funded volume and closed loans are cumulative, 2008–2025. Not licensed in CT or NY.
Why Work With Me
Personal Attention, Backed by More Than Any Local Shop Can Offer Alone
A bank hands you its own rate sheet. A local shop can only offer what's on their limited shelf. A big call-center lender means a queue, a ticket number, and a script built to close volume — not your situation. I work through Loan Factory's network of 240+ lenders, so you get the leverage of a national platform and the attention of one person who actually knows your file. Your loan gets measured against all 240+ offers — and since I am paid the same no matter which lender you land with, my only job is finding what's actually right for you.
More Doors Open
With 240+ lenders in the network, a decline from one doesn't mean a decline everywhere. Different lenders, different guidelines — I find the one that fits.
No Hidden Incentive
I'm paid the same regardless of which lender you choose. That means the only thing I'm optimizing for is what's actually right for you.
Actually Reachable
Evenings, weekends, whenever you need me. You get a person, not a queue and not an inbox that goes quiet after you sign.
If your agent sent you here, you’re in good hands both ways. I work closely with real estate agents.
One Less Thing to Carry
You are not juggling lenders, phone calls, and paperwork on your own. I carry that part.

Industry Expert
Straight Answers, Written Down
Real questions buyers ask me, answered in plain English
Browse a few recent articles below, or see everything in Learn.
- VA & Military
VA Funding Fee, Explained (and Who Doesn't Pay It)
What the funding fee actually costs, who’s exempt, and how it factors into your loan.
- First-Time Buying
Florida Down Payment Assistance in 2026: Every Program to Know
The Florida and Brevard programs that can help cover your down payment — most buyers never find out these exist.
Client Testimonials
Loan Factory has 21,000+ five-star reviews. That's not a coincidence.
That’s the platform behind me. Now it’s your turn.
“John is a miracle worker! I honestly never thought I would qualify for a loan, but he worked his magic and made the numbers work for me. I am so grateful for his expertise and persistence. If you think you can’t get approved, call John. THANK YOU!”
Jira S.
Google Review
“I bought 3 investment properties with John. His tenacity stood out to me. He always tried to find a way to make things work even when all the odds seemed to go against us. Im impressed with him”
Andy H.
Google Review
“John is absolutely amazing!! He is incredibly helpful, professional, and always goes above and beyond to make sure everything is taken care of. His dedication, and positive attitude really stand out!”
David V.
Google Review
Ready to Begin?
You don't need perfect. You need honest.
A 15-minute call costs you nothing and commits you to nothing. Let's find out which option is best for you.